



The payment that falls due next month
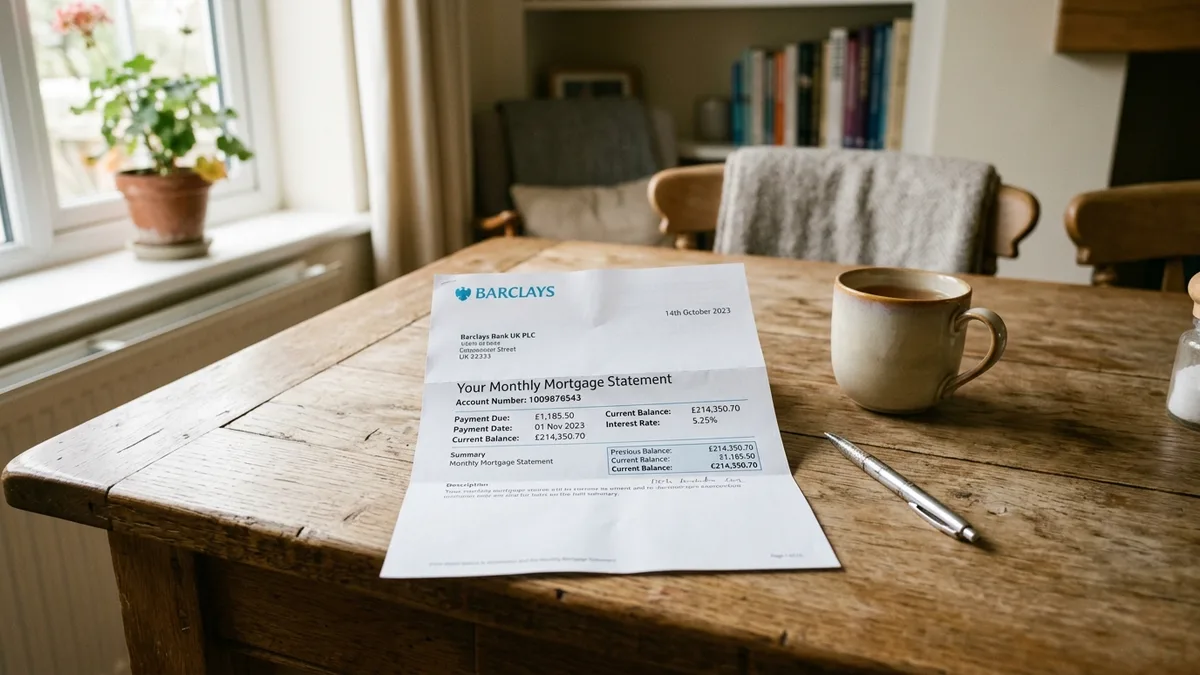
Whatever else is unresolved, the mortgage is due. It is the one obligation that does not wait for an agreement, and getting it wrong in the first month narrows every option that follows.
Couples across Aylesbury come to mediation with the same two questions: who pays it now, and what happens to the house in the end. They are different questions and they need answering in that order.
What the lender's position actually is

A joint mortgage makes both of you liable for the whole debt, not half of it. If one of you stops paying, the lender pursues whoever it can reach, and the arrears appear on both credit files. Any arrangement between you is invisible to the lender.
Tell the lender you have separated. Most have a dedicated team, and a temporary interest only arrangement, a payment holiday or a term extension are all considerably easier to arrange before a payment is missed than after.
Whether the house can stay
Only the lender decides this, through a transfer of equity, and it will only agree if the remaining party can carry the whole loan on their own income under current affordability rules.
This is where a large number of separations meet a hard limit. A mortgage two incomes supported comfortably frequently fails affordability on one, and no agreement between the parties changes that. Speak to a broker in the first fortnight: knowing what is possible reshapes the entire negotiation, and it is far better known early than in month six.
The three realistic outcomes

Sell and divide the equity. Clean, and it is the only option that definitely works.
One party buys the other out, by transfer of equity, usually funded by a remortgage or by offsetting against a pension or savings.
A deferred sale, where the property is held and sold on a defined trigger: the youngest child finishing education, the resident party remarrying or cohabiting, or a fixed date. It keeps a home together and carries a real cost for the person who stays, who maintains a property they cannot refinance and faces a sale at an age when borrowing again may be harder.
Protecting your position
Obtain the title register from HM Land Registry so you know who legally owns what. It costs a few pounds.
If the home is in the other person's sole name and you are married, register a home rights notice against the title. It is a form, it costs nothing, and it prevents the property being sold or further charged without you knowing. Home rights arise under the Family Law Act 1996 and they end on divorce unless the court orders otherwise, so it is a step to take early.
How the payments are treated at the end
Not automatically returned. The court has a discretion and outcomes vary.
Where one party pays the mortgage while the other lives there rent free, the payments are often treated as broadly balancing the occupation, particularly where children live there. Where one party pays the mortgage on an empty property, or is also paying rent elsewhere, an equity credit is more likely.
The way to reduce that uncertainty is to agree the treatment in advance, in writing, rather than argue about it at the end. That is exactly what mediation records.
Writing a deferred sale properly
Where the sale is deferred, the detail is the whole thing. Who pays the mortgage. Who pays for repairs and what counts as a repair rather than an improvement. What happens if the payer stops. Whether the resident party can let a room. Exactly how the proceeds divide, in percentages or in a formula. And what triggers the sale, defined so precisely that nobody can argue about whether it has happened.
An order that deals with the house in detail and says nothing about the contents, or that names a trigger without saying who serves notice of it, is the order that comes back.
If the mortgage genuinely cannot be paid
Speak to the lender before missing a payment. Speak to a broker about a term extension or a temporary interest only period. Take free debt advice from Citizens Advice, StepChange or National Debtline, none of which charge.
And consider selling sooner rather than later. A sale on your own timetable, out of arrears, produces a materially better outcome for both of you than one forced by a lender, and the couples who reach that conclusion early are usually glad they did.


 Face to face sessions
 Online and remote mediation
 Evening and weekend appointments